

CNX Resources has gotten torched over the last six months - since April 2026, its stock price has dropped 20.6% to $31.51 per share. This might have investors contemplating their next move.
Following the drawdown, is now an opportune time to buy CNX? Find out in our full research report, it’s free.
Why Does CNX Stock Spark Debate?
Tracing back to operations that began in 1860, CNX Resources (NYSE:CNX) drills for and produces natural gas from underground shale formations in Pennsylvania, Ohio, and West Virginia.
Two Things to Like:
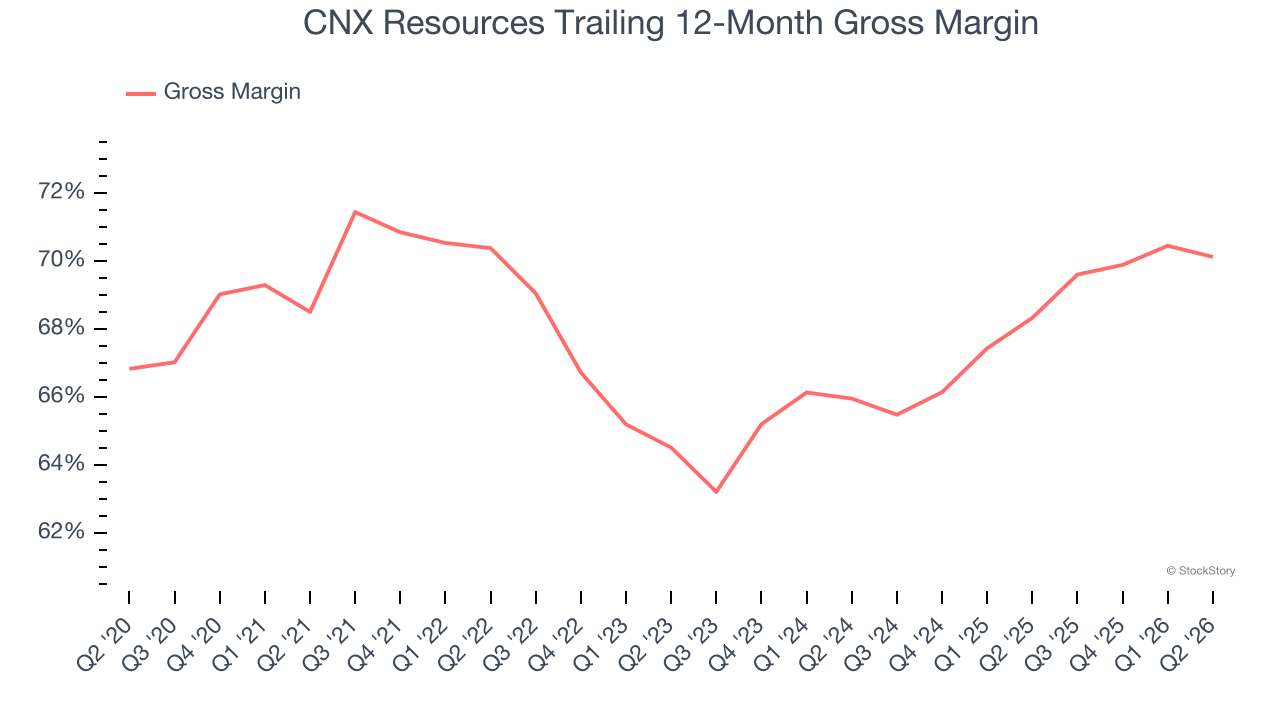
1. Elite Gross Margin Powers Best-In-Class Business Model
In any given year, energy gross margins are heavily influenced by prices, hedging, and cost inflation, but over a full cycle these gross margins reveal which producers are structurally advantaged through superior “rock” quality, infrastructure access, and cost position.
CNX Resources, which averaged 68% gross margin over the last five years, exhibits impressive unit economics in the sector. It means the company will remain profitable at lower commodity prices than peers with inferior gross margins and serves as an excellent starting point for ultimate operating profits and free cash flow generation.
2. Excellent Free Cash Flow Margin Boosts Reinvestment Potential
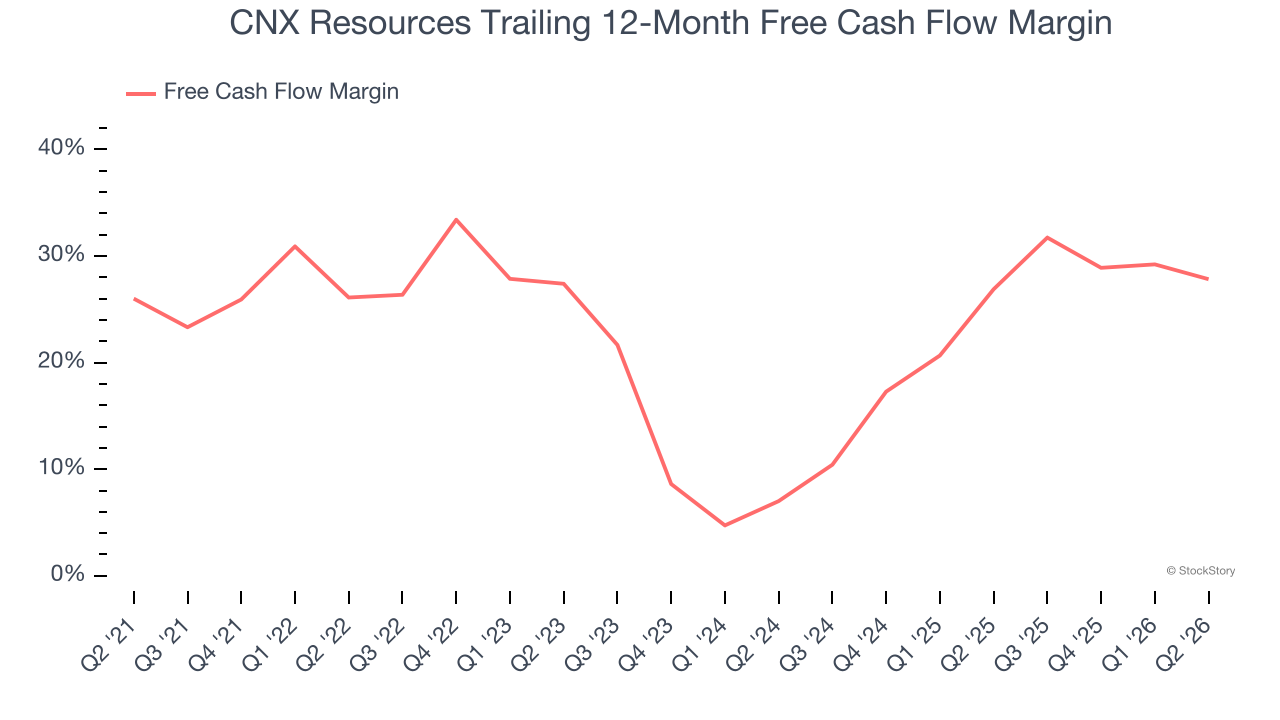
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
CNX Resources has shown terrific cash profitability, driven by its lucrative business model that enables it to reinvest, return capital to investors, and stay ahead of the competition. The company’s free cash flow margin was among the best in the energy upstream and integrated energy sector, averaging 23.5% over the last five years.
One Reason to Be Careful:
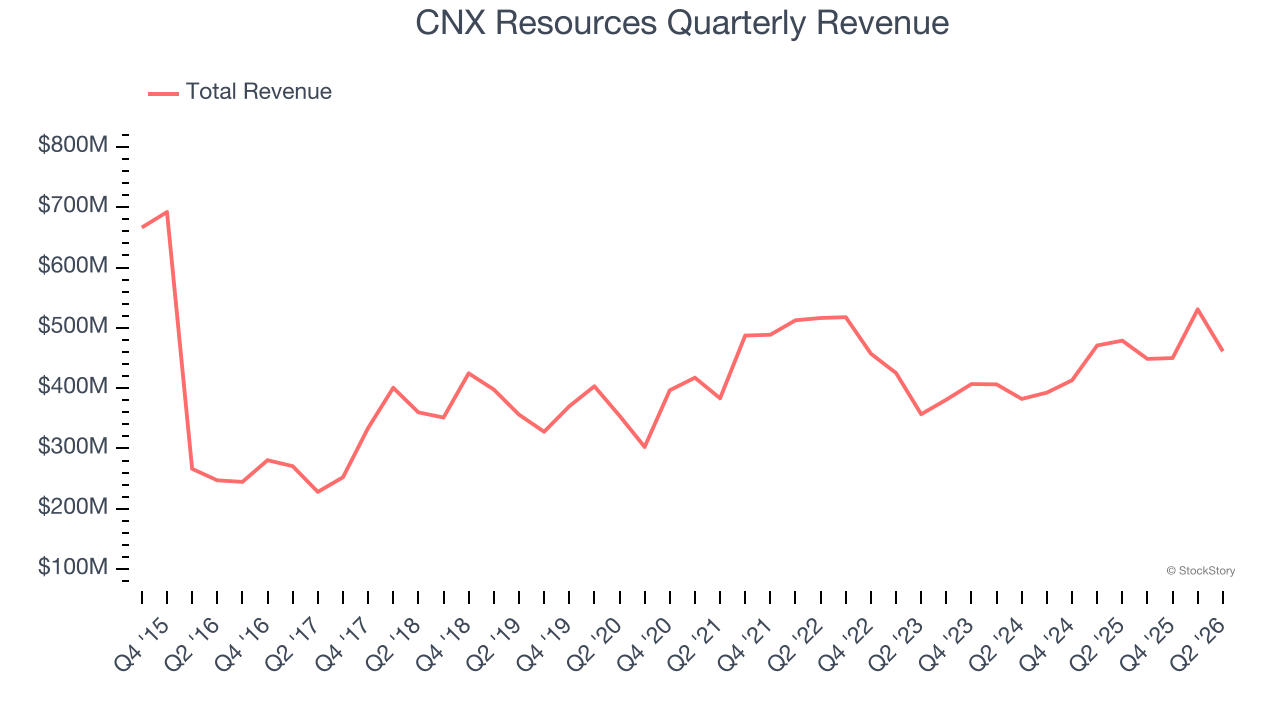
Long-Term Revenue Growth Disappoints
Cyclical sectors like Energy often flatter weaker operators during favorable price environments, but a longer-term lens separates those from businesses that can consistently perform across market cycles. Unfortunately, CNX Resources’s 4.7% annualized revenue growth over the last five years was sluggish. This wasn’t a great result compared to the rest of the energy upstream and integrated energy sector, but there are still things to like about CNX Resources.
Final Judgment
CNX Resources’s positive characteristics outweigh the negatives. After the recent drawdown, the stock trades at 9.8× forward P/E (or $31.51 per share). Is now a good time to buy? See for yourself in our in-depth research report, it’s free.
Stocks We Like Even More Than CNX Resources
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.