

Over the last six months, Tesla’s shares have sunk to $365.62, producing a disappointing 6.9% loss - a stark contrast to the S&P 500’s 14% gain. This might have investors contemplating their next move.
Is now the time to buy Tesla, or should you be careful about including it in your portfolio? Check out our in-depth research report to see what our analysts have to say, it’s free.
Why Do We Think Tesla Will Underperform?
Even with the cheaper entry price, we don’t have much confidence in Tesla. Here are three reasons why there are better opportunities than TSLA, plus one stock we’d rather own.
1. Sales Volumes Stall, Demand Waning
Revenue growth can be broken down into changes in price and volume (the number of units sold). While both are important, volume is the lifeblood of a successful Automobile Manufacturing company because there’s a ceiling to what customers will pay.
Over the last two years, Tesla failed to grow its units sold, which came in at 480,126 in the latest quarter. This performance was underwhelming and implies there may be increasing competition or market saturation. It also suggests Tesla might have to lower prices or invest in product improvements to accelerate growth, factors that can hinder near-term profitability. 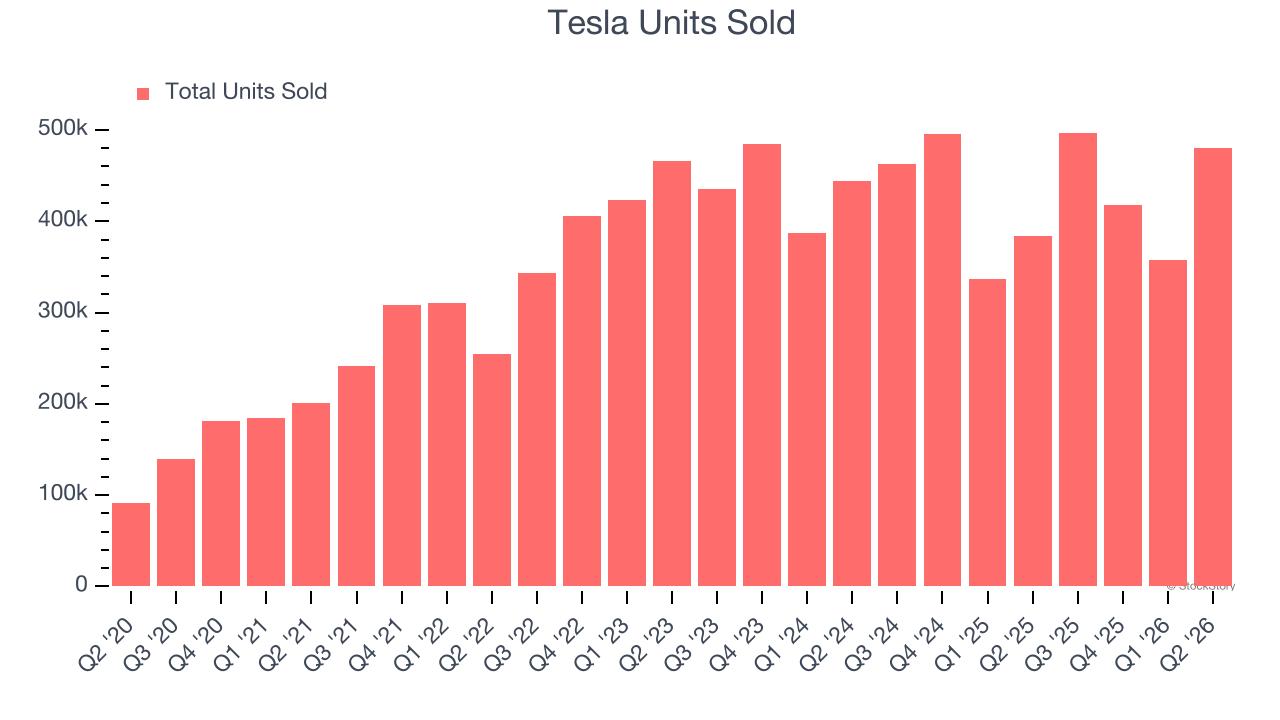
2. Free Cash Flow Margin Dropping
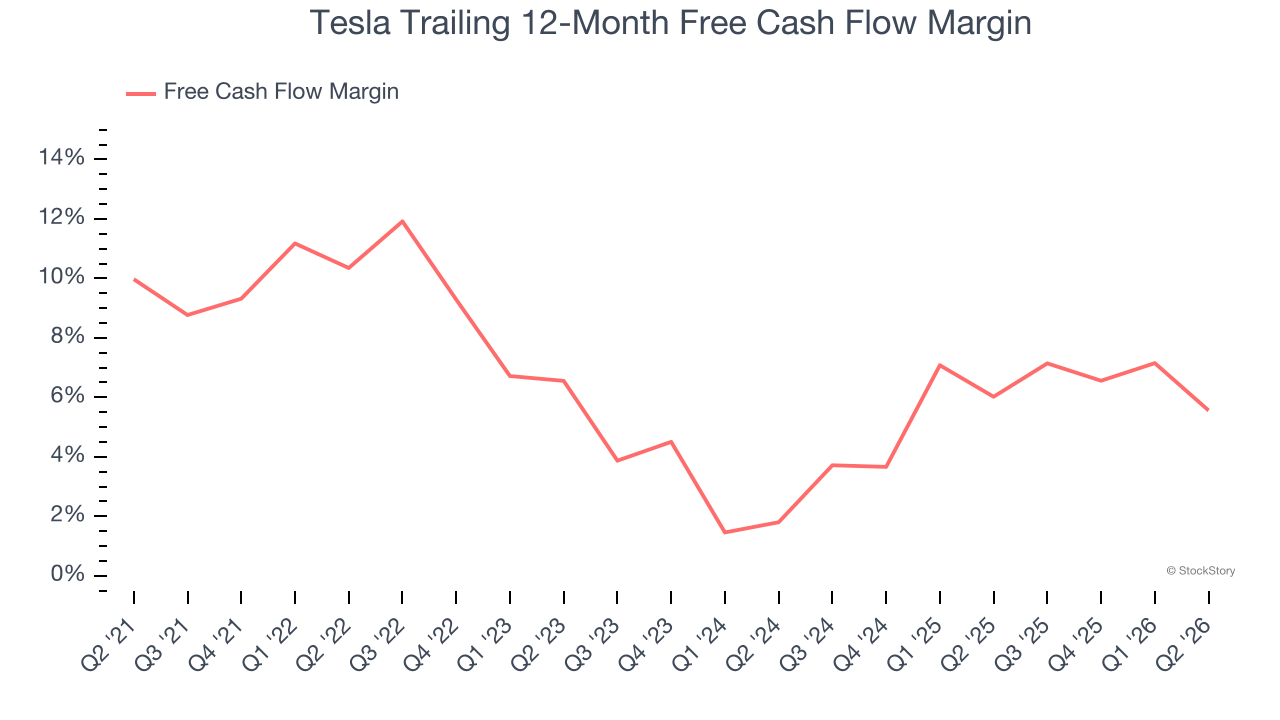
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills or invest for the future.
As you can see below, Tesla’s margin dropped by 4.8 percentage points over the last five years. Continued declines could signal it is in the middle of an investment cycle as it pursues new AI technologies such as a robotaxi or humanoid robot fleet. Tesla’s free cash flow margin for the trailing 12 months was 5.6%.
3. New Investments Fail to Bear Fruit as ROIC Declines
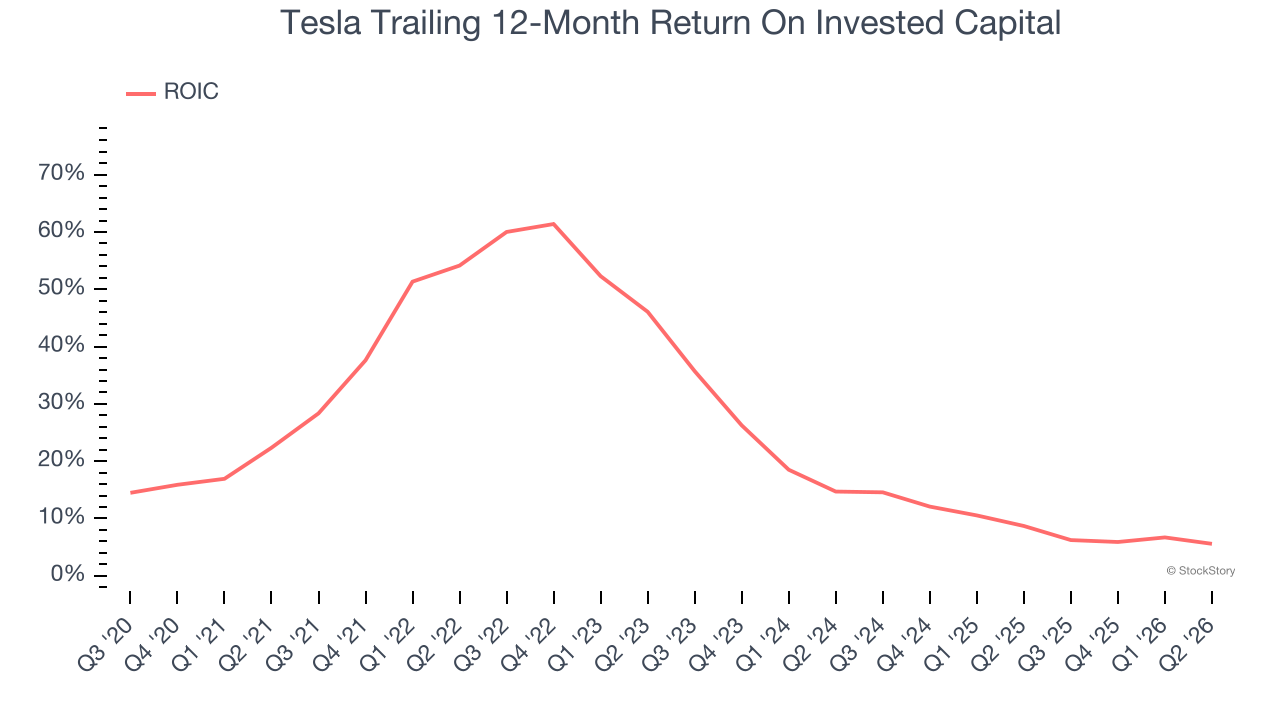
ROIC, or return on invested capital, is a metric showing how much operating profit a company generates relative to the money it has raised (debt and equity).
While Tesla’s ROIC fell recently due to its price cuts, the broader trend is still healthy as its ROIC is higher than a few years ago. This is because it’s investing aggressively to capture the AI opportunity. Only time will tell if these investments bear fruit in higher long-term ROICs.
Final Judgment
We see the value of companies helping their customers, but in the case of Tesla, we’re out. After the recent drawdown, the stock trades at 185.1× forward price-to-earnings (or $365.62 per share). At this valuation, there’s a lot of good news priced in - we think other companies feature superior fundamentals at the moment. We’d suggest looking at an all-weather company that owns household favorite Taco Bell.
Stocks We Like More Than Tesla
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.